
Forex Market Structure: Participants, Liquidity and Trading Sessions
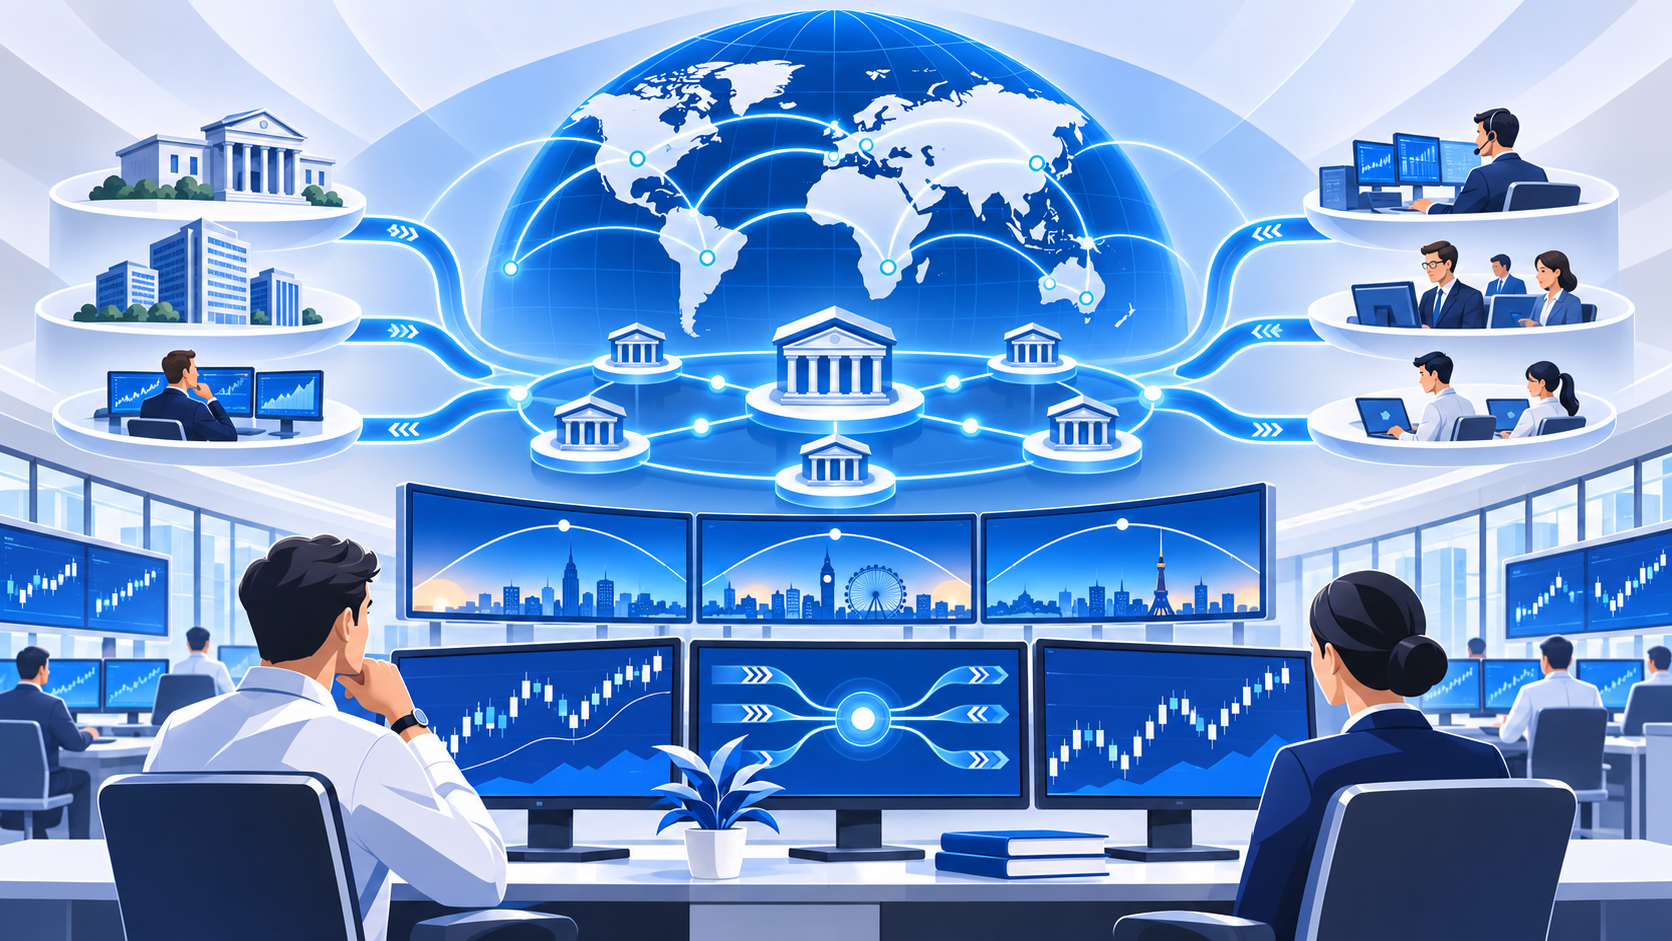
The Forex market is a decentralised, predominantly over-the-counter (OTC) network in which banks, asset managers, corporations, liquidity providers and other counterparties trade currencies through bilateral relationships and electronic venues. Market structure matters because execution conditions, available liquidity, information and even quoted prices can vary by participant, platform, order size and time of day. It is not simply a globally shared order book where everyone sees the same liquidity.
This guide explains how participants interact; why liquidity is fragmented; how dealers manage customer orders; how session overlaps influence conditions; and how trades are confirmed, financed and settled. It also separates institutional spot FX from the retail leveraged instruments that reference currency pairs.
The size of the modern institutional FX market
The Bank for International Settlements’ final 2025 Triennial Survey places global OTC FX turnover at approximately US$9.5 trillion per day in April 2025, across spot and derivatives. Turnover is the face value of transactions, not the net amount of fresh capital invested or a measure of net risk transferred. FX swaps, which facilitate funding and hedging, account for a large part of it.
The BIS analysis of execution in December 2025 highlights how electronic trading sits alongside bilateral, relationship-based transactions. Market visibility is incomplete because dealers can internalise matched customer flows rather than displaying each trade publicly. A transaction can be legitimate and sizeable while leaving little trace on an exchange-style consolidated tape.
Who makes up the Forex market?
The roles of banks, dealers, investment managers and other institutions are also compared in Financial Market Participants Explained.
Dealer banks and their customers
Major dealer banks offer exchange rates to corporate treasurers, institutions and other banks. In a principal transaction the bank becomes the customer’s counterparty, buys or sells the currency, and then manages the resulting inventory. In an agency-style arrangement an intermediary may route an order toward one or more liquidity sources. These structures matter for conflicts, mark-ups, execution quality and the allocation of risk.
A bank may quote a customer in EUR/USD and reduce that exposure by finding an offsetting customer request. If its incoming euro buys and euro sells offset, it need not hedge the gross amount on an external venue. BIS research reported that major dealers were able to match more than 80% of customer spot volumes internally in important markets around April 2025. That is not a universal internalisation rate for every provider, instrument or day.
Non-bank electronic market makers
Specialist non-bank firms compete with banks by supplying executable prices using technology, inventory models and access to multiple venues. High-speed quoting can improve competition under normal conditions, yet displayed size may shrink sharply during a surprise announcement. A price provider is not obligated to offer unlimited liquidity at its last displayed quote.
Asset managers, insurers and pension funds
International portfolios create recurring currency exposures. A UK pension fund buying US corporate bonds can hedge dollar exposure separately from the bond’s interest-rate or credit risk. Portfolio rebalancing, valuation shifts and hedge-ratio adjustments may generate very large FX flows independent of any short-term trading opinion.
Corporations and central banks
Importers and exporters convert cash flows, hedge planned receipts and pay overseas obligations. Central banks hold reserves and conduct monetary policy; some intervene in currency markets. Their objectives differ from speculative traders’, and a large trade can arise from a known future invoice rather than from a price forecast.
OTC dealing is not a single exchange
The FX market includes direct dealer-to-client streams, requests for quotes (RFQs), electronic brokers, multidealer platforms, central limit order books and voice execution. Platforms differ in whether orders are anonymous, disclosed, firm, indicative or subject to last look. Some venues display executable depth; others show bilateral quotations only to entitled counterparties.
A central limit order book matches priced bids and offers according to venue rules. An RFQ platform sends a proposed transaction to selected liquidity providers, which may respond with prices. A dealer’s proprietary stream is a two-way price offered under an existing commercial or credit relationship. There is no single universally correct execution channel: size, immediacy, information leakage, credit and liquidity needs all change the evaluation.
Why two screens can show different prices
A displayed EUR/USD rate may be a market-data indicative price, a dealer’s streaming quote for a permitted notional size, or an exchange-traded derivative quote using different conventions. One platform may aggregate several banks while another offers only its own liquidity. Prices change continuously, and access to liquidity depends on the actual counterparty relationship, execution rules and data latency. A small price difference is not necessarily an arbitrage opportunity after costs.
Bid–ask spreads, depth and market impact
For more on the difference between a visible quote and executable market depth, read Market Liquidity Explained.
The bid–ask spread is the difference between the price at which a dealer buys and sells the base currency. Market depth describes how much can be bought or sold at available price levels. Market impact is the price movement caused by executing an order. These are related but distinct: a narrow top-of-book spread can coexist with poor depth and high impact for a large order.
Suppose an institutional customer wants to purchase €40 million. One liquidity source offers €5 million at 1.08002, another €10 million at 1.08004 and a third €25 million at 1.08010. Ignoring fees and slippage, the weighted-average executable price would be 1.0800775 dollars per euro, calculated as (5×1.08002 + 10×1.08004 + 25×1.08010) ÷ 40. This is 0.575 conventional pips above the best displayed offer, highlighting the difference between an attractive headline quote and the actual price of a large order.
The example assumes all quoted volumes remain available during execution. In real markets, quotes may update or disappear, partial fills may occur and the order itself may reveal information. A large order can therefore cost more than a static snapshot suggests.
Internalisation and the price-discovery process
When a dealer matches customers internally, price formation may still depend on external reference markets and risk models. Internalisation can reduce external hedging and information leakage, but it can also make the broader market less transparent about gross flows. One should avoid inferring the sign of aggregate buying or selling from an individual venue’s traded volumes alone.
London, New York, Tokyo and Sydney: trading sessions
For an overview of the market’s decentralised trading and settlement arrangements, see How the Global Forex Market Works.
FX activity follows the overlapping business hours of global financial centres. Sydney and Asia lead into the European day, London overlaps with New York, and the American session leads toward the next Asian open. Often described as a 24-hour weekday market, access is nevertheless product-, venue-, holiday- and counterparty-specific.
| Centre | Local market emphasis | Why it matters |
|---|---|---|
| Sydney | Australasian business hours | Opening-week liquidity and regional economic events |
| Tokyo | Japanese and wider Asian business day | JPY markets, Japanese data, regional flows and fixings |
| London | European and UK financial day | Large global dealing hub, European data and institutional hedging |
| New York | US financial day | US data, dollar funding, US asset-market flows and monetary policy |
These are activity windows, not promises of exact opening and closing times for every institution. A forex chart spanning London and New York should be labelled using the actual date and timezone; daylight-saving transitions differ between the UK, United States and other jurisdictions. Japan does not observe daylight saving, meaning a fixed UTC chart can conceal seasonal shifts in overlap.
April 2025 survey data put the UK’s share of global FX sales-desk turnover at roughly 38% and the US share around 19%, on the survey’s stated measurement basis. These geographical figures measure the location of reporting sales desks, not the nationality of buyers or the source of currency demand. Source: BIS Triennial Survey.
Why session overlaps affect spreads and volatility
When active dealing centres overlap, more participants may simultaneously quote, hedge and execute, which can improve accessible liquidity for common pairs. But the relationship is conditional. High volume during a major surprise can coincide with wider spreads and faster prices because liquidity providers face greater uncertainty and inventory risk.
A useful distinction is between volume, volatility and liquidity. Volume counts transactions; volatility measures variation in prices; liquidity concerns the ease of transacting at a reasonable cost without moving the market. A market can have very high volume and poor liquidity if the order imbalance is severe.
Fixings, benchmarks and scheduled market events
Institutional FX flows often cluster around index rebalancing, benchmark fixing windows, options expiries, settlement cut-offs and economic announcements. Benchmarks are subject to published methodologies and governance; a fixing is not simply ‘the official close’ of a market without a central close. Participants may hedge benchmark exposure over time to manage slippage and market impact.
Price behaviour near a known event may reflect temporary execution demand rather than changed long-run macroeconomic value. This explains why a currency can move abruptly and reverse, or why a strong data release may not produce a lasting trend.
What happens when an FX trade is executed?
Spot currency exchange, forwards and listed FX futures follow different rules. Compare Forex Spot, Forward, Futures and Swap Markets.
- Pre-trade: counterparty eligibility, limits, market data, instrument and value date are established.
- Execution: currency pair, side, amount, rate and settlement instructions are agreed under the relevant agreement or venue rules.
- Confirmation: both sides match economic terms and resolve discrepancies.
- Risk management: trading exposure and settlement instructions are monitored; counterparty and funding risks are assessed.
- Settlement: currency payments are completed on the value date, sometimes using payment-versus-payment arrangements.
Spot transactions in many major pairs conventionally settle two good business days after execution, although exceptions and holiday calendars matter. Settlement risk is a distinct hazard: a participant might deliver the currency sold but not receive the currency bought. The BIS 2026 settlement research notes that payment-versus-payment systems mitigate this risk, but not every transaction is covered. Source: BIS FX settlement analysis.
What is last look and why is it debated?
Some FX liquidity providers use last look, a mechanism by which a provider can perform specified validity and price checks before accepting or rejecting a trade request. It may serve risk controls, but its implementation creates fair-treatment and information-handling questions. Traders should read venue disclosures rather than assume that a displayed price equals guaranteed execution.
The FX Global Code (updated December 2024) establishes voluntary global principles of good practice covering execution, information sharing, risk management and settlement. It does not replace law or remove the need for suitability and product-risk assessment.
Why retail Forex can be structurally different
A retail customer trading a rolling spot FX product or CFD may not receive the underlying currencies. Instead, the customer holds a contract with the provider referencing the quoted pair. Margin, financing, stop orders, negative-balance protections and legal counterparty structure depend on the product and jurisdiction. Institutional spot volumes and bank market-making practices cannot be used to imply that retail leverage is safe.
For a hypothetical £2,000 margin deposit supporting a £40,000 notional exposure, a 2% adverse move before fees would represent an £800 notional loss, or 40% of the deposit. This simplified illustration ignores liquidation rules, currency conversion and price gaps. The economic exposure is determined by the larger notional position, not the initial deposit.
How to analyse FX market quality
Professional execution evaluation looks beyond a spread snapshot. Compare effective spread against a recognised reference, quote availability, fill ratio, rejection or cancellation rates, adverse slippage, market impact, realised execution cost and settlement performance. The relevant measures depend on whether the participant is a bank, asset manager, corporate treasury or retail customer.
Time of day, event calendars, trade size, currency pair and tenor should be recorded, because comparing an Asian-session EUR/GBP order with a London–New York EUR/USD order can produce misleading conclusions about providers. For complex derivatives, credit availability and funding costs can dominate apparent execution differences.
Key takeaways
- FX is highly liquid in aggregate but fragmented across counterparties, products and venues.
- Banks can internalise substantial customer flow; not all trades appear in a central order book.
- Top-of-book spread, market depth, market impact and execution quality are separate measures.
- Session overlaps affect activity, while daylight-saving rules make simplistic time tables unreliable.
- Execution and settlement are different stages, each carrying distinct risks.
- Wholesale Forex mechanisms should not be confused with the risks and contractual design of retail leveraged trading.
Frequently asked questions
Where does Forex trading take place?
Primarily through electronic and bilateral OTC trading relationships among banks, institutions and other participants, with some exchange-traded FX products. There is no single venue responsible for all spot transactions.
Does 24-hour trading mean constant liquidity?
No. Trading access and liquidity change with sessions, currency pairs, holidays and events; prices can gap or widen despite nominal market availability.
Why do brokers show different exchange rates?
They may source different liquidity, show different sizes or apply different mark-ups, execution rules, fees or time stamps.
What is liquidity internalisation?
A dealer offsets customer buying and selling on its own book rather than externally hedging each transaction.
Is last look the same as a guaranteed quote?
No. Last look involves defined acceptance or rejection checks; venue disclosures determine how it operates.
Sources and further reading
- BIS, The FX Trade Execution Landscape, December 2025.
- BIS, Global FX Markets When Hedging Takes Centre Stage, December 2025.
- BIS, 2025 FX Settlement Survey Analysis, June 2026.
- Global Foreign Exchange Committee, FX Global Code.
Educational notice: General education only; not personalised financial advice or a recommendation to transact. Leveraged FX trading can produce substantial losses.